Analysis
Alphabet's AI Spending Surge Puts Gemini Growth Under Investor Pressure
Alphabet reported strong cloud and Gemini momentum while raising its 2026 capital expenditure outlook, forcing investors to weigh AI demand against negative free cash flow and rising infrastructure costs.
By Elvin C ·
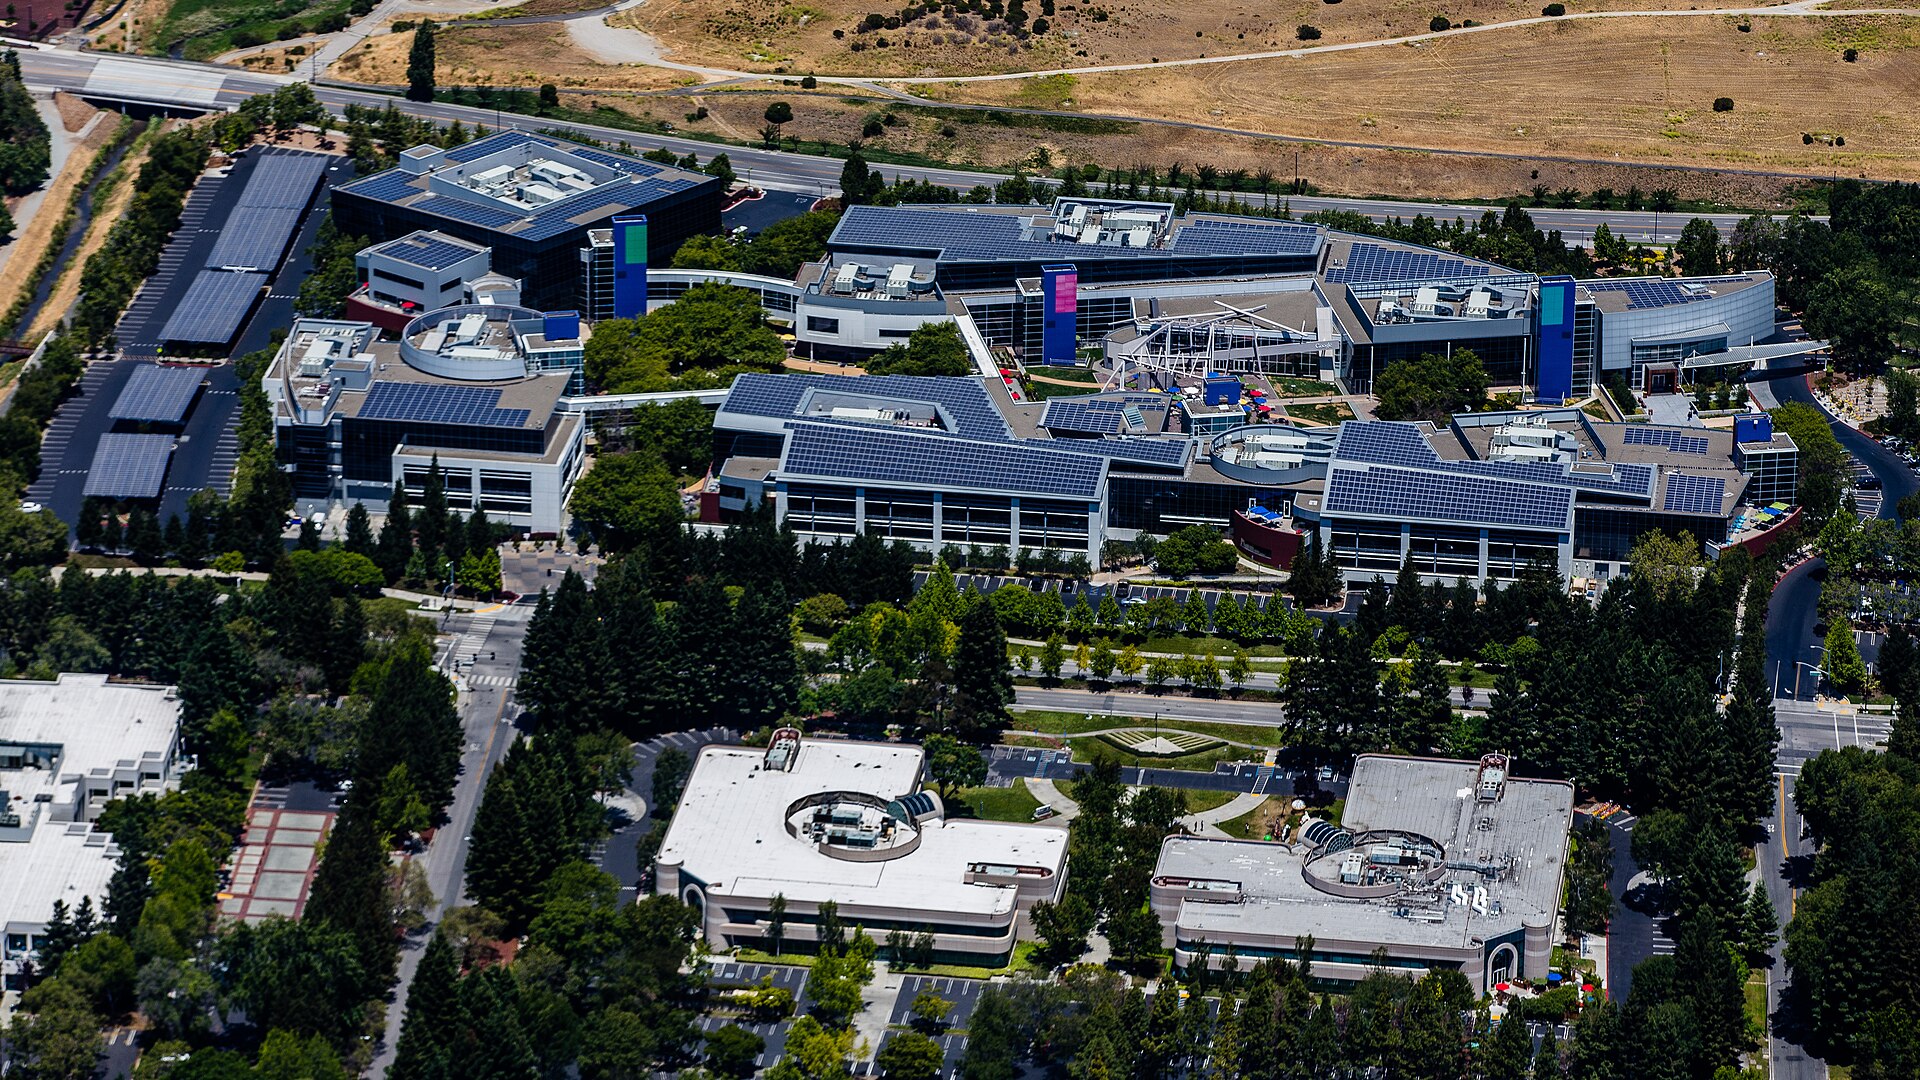
Alphabet gave investors the clearest early read of this earnings season's AI trade, and the message was mixed in exactly the way the market now expects. Google parent Alphabet reported strong revenue and cloud momentum, with Axios citing 82% growth in Google Cloud and Gemini monthly active users reaching 950 million. At the same time, Axios reported that free cash flow turned negative in the quarter and that Alphabet raised its 2026 capital expenditure guidance to $195 billion to $205 billion. The stock reaction showed the central question for AI investors: growth is real, but the price of keeping up is rising.
The Guardian reported that Alphabet's second-quarter revenue reached $119.8 billion and that earnings beat Wall Street expectations. Those numbers are not weak. They confirm that Google's core business remains formidable while AI demand is expanding across cloud, search, and consumer products. Yet the market is not asking only whether revenue is growing. It is asking whether the incremental AI dollar produces enough margin to justify a capital plan that would have looked extraordinary only a few years ago.
The market question starts with the difference between adoption and return. Gemini approaching 1 billion monthly active users is a distribution milestone. AI Overviews reaching billions of users is a product milestone. Google Cloud's acceleration is a demand milestone. None of those figures by themselves answers whether Alphabet can defend operating margins while building the infrastructure required to keep those products fast and competitive.
The spending increase also comes after Google released cheaper Gemini models aimed at agent workloads and lower-cost production use. That combination is revealing. Alphabet is spending heavily on infrastructure while also trying to reduce the unit cost of inference. The company knows customers will not send every task to the most expensive model. The durable business will depend on routing, smaller models, custom chips, and software that keeps utilization high.
Search remains the most sensitive part of the story. Axios reported that search revenue rose 17% from a year earlier to $63.3 billion but came in slightly below Wall Street expectations. That is not a collapse. It is a warning light. Google is trying to rebuild the user experience around AI answers while preserving the advertising engine that funds the rest of the company. If AI summaries reduce clicks, change ad formats, or shift query behavior faster than monetization adapts, the market will press harder.
The cloud number gives Alphabet its strongest counterargument. An 82% growth rate suggests customers are buying AI infrastructure and services at scale. Business Insider reported that Google Cloud revenue reached $24.8 billion and that backlog expanded sharply, signs that enterprise demand is not only theoretical. If those commitments convert into durable, high-margin workloads, the capex story becomes easier to defend.
The risk is timing. Data centers, chips, and power commitments are long-lived. Consumer product cycles and enterprise model preferences can change quickly. Alphabet may be right to build ahead of demand, but investors will punish evidence that the company is overbuilding or that AI revenue is being bought with margin compression. Negative free cash flow is not fatal for a company with Alphabet's balance sheet. It is a signal that the AI transition is changing the cash profile of even the strongest platforms.
Competitive pressure leaves Alphabet little room to spend cautiously. OpenAI and Anthropic are pushing enterprise products. Meta is spending aggressively on its own models and infrastructure. Amazon and Microsoft are defending cloud share. Chinese open models are putting price pressure on closed systems. In that environment, the cost of underinvesting may be higher than the cost of explaining a difficult quarter.
Alphabet's earnings therefore do not settle the AI trade. They sharpen it. The company has demand, users, cloud growth, models, chips, and distribution. It also has a capital expenditure curve that forces investors to ask when the infrastructure becomes self-funding. That is the test every hyperscaler will face this season.
For now, Alphabet's answer is scale. It is using its balance sheet to make AI unavoidable across search, cloud, Android, Workspace, and consumer assistants. The market's answer is more conditional. It wants evidence that scale still produces cash after the data center bill arrives.
Topics: Alphabet, Google, Gemini, AI spending